

Moneyweb and Daily Star’s coverage of the Bull Run
Spain has had a whirlwind couple of weeks, with last week’s total solar eclipse attracting many to its shores. Early July also saw the return of the annual running of the bulls in Pamplona, which drew typical crowds.
Just a few days after that, Spanish captain Rodrigo ‘Rodri’ Hernandez Cascante lifted the FIFA World Cup trophy in New York. Meanwhile, the capital Madrid has been grappling with heatwaves and destructive wildfires. In Ceuta, a Spanish enclave in North Africa, there was a brief surge of migrants from neighboring Morocco.
Read:
A cocaine bust in Spain traces back to Wall Street
Spain triumphs over Argentina in FIFA World Cup finals
Czech billionaires have a significant presence in the European M&A scene
Although Spain boasts a large and sophisticated economy, it typically remains under the radar and doesn’t influence global markets. However, with its current prominence, we can spotlight four key takeaways for South African investors.
- Countries can bounce back from severe economic downturns.
- While climate change presents risks, it also offers opportunities through the green transition.
- Large-scale immigration brings both advantages and challenges.
- Equity markets can rally even without a compelling narrative when listed companies are undervalued but continue to grow their profits quietly.
The pain in Spain
It’s easy to overlook that Spain was in deep trouble not long ago.
Together with other Mediterranean economies like Portugal, Italy, and Greece, Spain faced a series of economic and financial crises from 2008 to 2013.
These nations were often pejoratively referred to as the PIGS.
10-year government bond yields, %
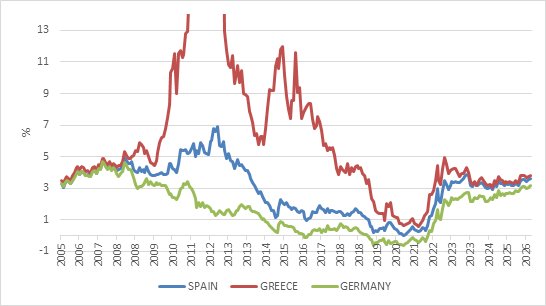
Source: LSEG Datastream. Note that Greece’s yield peaked at 34% in 2012.
The crisis originated from a pre-2008 boom, driven by cheap credit and declining interest rates. Following its entry into the eurozone in 1999, Spain experienced reduced borrowing costs that aligned closely with Germany’s.
This set the stage for an enormous real estate bubble, which was linked to a dramatic rise in private debt (see the chart below). When this bubble burst in 2008, mirroring global trends, the consequences were dire. Construction and related jobs vanished, leading unemployment to skyrocket to 25%, with youth unemployment hitting 50%.
Spanish banks ended up with significant quantities of bad loans, jeopardizing their stability.
Surging tax revenues during the boom masked a growing deficit during the bust, leading to increased government borrowing. However, the uncovering of a massive gap in Greek public finances in 2010 pushed up borrowing costs for all PIGS nations.
In 2010, S&P Global downgraded Spain’s credit rating from AAA to BBB- by 2012.
This downgrade hampered the Spanish government’s funding abilities, making it even more challenging for banks whose government bond holdings were plummeting in value. Analysts cautioned about a potential “doom loop” linking fragile government finances and weak bank balance sheets across the PIGS, raising fears of the euro project’s disintegration.
The ensuing economic struggles led to a discontented populace and significant political upheaval, including the rise of new political parties.
Spain debt-to-GDP ratios
ADVERTISEMENT
CONTINUE READING BELOW
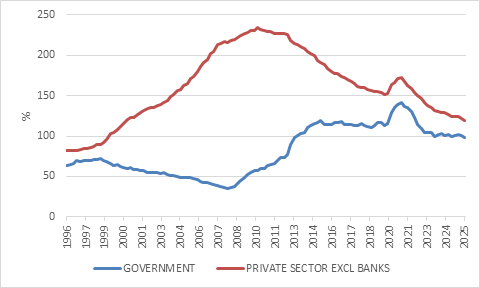
Source: Bank for International Settlements
Initially, the recovery from economic calamity was slow, but it eventually gained traction over time. Spain requested €100 billion from the European Stability Mechanism in 2012 to recapitalize its banks, ultimately utilizing €41 billion.
Once the banking sector underwent cleanup and consolidation, it was positioned to bolster the economy rather than hinder it.
Labour regulations were relaxed to incentivize hiring, and businesses increasingly turned to exports to compensate for a sluggish domestic market.
Private debt levels gradually decreased. The tourism sector flourished, eventually making Spain the world’s second-most-visited country by international arrivals in 2017, coming in just after France.
Despite the challenges posed by COVID-19, Spain’s recovery has outpaced other major Eurozone economies, with unemployment dropping to 9.8% by the second quarter of this year.
Notably, Spain has achieved healthy annual growth rates of 2% to 3% in recent years, even while Germany has stagnated. This marks a complete reversal from the early 2010s, when Germany was seen as Europe’s growth powerhouse as well as its fiscally responsible sanctuary.
Today, Germany’s renowned industrial sector faces fierce competition from Chinese manufacturers and lacks access to affordable Russian gas.
Real economic growth in Europe
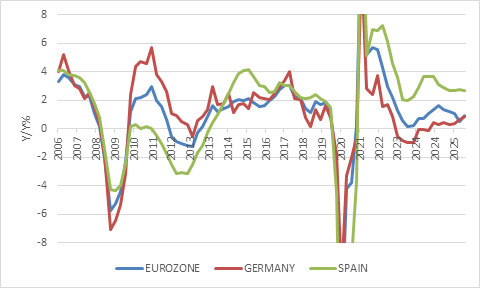
Source: LSEG Datastream. Axis truncated around the pandemic
Robust economic growth has contributed to the stabilization of government finances.
The public debt-to-GDP ratio, which nearly tripled from 2008 to 2020, has seen a slight decline, and Spain has now secured an A+ credit rating.
Government bond yields have largely realigned with those of Germany.
It’s worth noting that Greece has made an even more remarkable recovery from an economic depression that saw its bonds downgraded to junk status (CCC), and its stocks classified as emerging market equities. Through a combination of rigorous reforms and the passage of time, Greece’s economy has returned to growth, and its bonds have been upgraded to investment grade status (in 2023), while MSCI has announced the return of its stocks to developed market indexes next year.
Both Spain and Greece have benefited from European Union funding, emphasizing that countries can recover from economic crises with the right strategies.
It’s also critical to recognize that major crises often follow extraordinary booms, a phenomenon that has not been witnessed domestically in quite some time.
Climate crisis and opportunity
Spain’s resurgence has been aided by its energy policies.
ADVERTISEMENT:
CONTINUE READING BELOW
Decades of investment in renewable energy mean that more than half of Spain’s electricity is sourced from wind and solar. In contrast to many gas-dependent European nations, Spain has been better equipped to handle surges in fossil fuel prices prompted by conflicts in Ukraine and Iran.
Read: Heat becoming a significant economic shock for an ill-prepared Europe
While not every European country has Spain’s abundant sunshine, it highlights a potential solution to one of Europe’s significant geostrategic vulnerabilities: being a net energy importer.
Currently, Spain exports not just electricity to its neighbors but also expertise and equipment, including to South Africa, where Spanish firms are engaged in developing solar and wind farms.
Like Spain, South Africa holds immense potential for renewable energy. Enhancing electricity production and transmission infrastructure represents one of the country’s greatest economic opportunities, not only for decarbonization but also for stimulating economic growth.
Decarbonization remains urgent, however. Recent wildfires and heatwaves in Spain illustrate the nation’s susceptibility to extreme weather events driven by climate change.
Indeed, Europe is warming faster than other regions, according to Copernicus, an EU scientific body. Severe drought has economic ramifications, impacting transport and electricity generation, leading to shut-downs of several nuclear plants. The Rhine River is currently at its lowest level at the Kaub measuring station in Germany since records began 150 years ago.
This situation has rendered the river too shallow for most vessels, positioning Kaub alongside Hormuz as a critical chokepoint for shipping, disrupting the north-south flow of goods across Europe.
East-west transport is equally strained with record-low water levels in the Danube.
Migration nations
In economically disadvantaged regions worldwide, climate change will intensify migration as droughts and floods compel individuals to seek work and sustenance elsewhere. In extreme cases, certain areas could become so hot and humid as to be virtually uninhabitable.
The reverse of this migration surge in Africa, Asia, and Latin America is the influx of people into wealthy, aging nations facing diminishing labor forces.
Spain’s median age stands at 46.3, with a fertility rate of only 1.2 children per woman, significantly below the replacement level. This demographic situation is slightly worse than the EU averages of 44.9 and 1.3, respectively. Eurostat predicts that the EU population will peak in 2029 at 453 million. This unfavorable demographic outlook represents Europe’s second significant geostrategic weakness.
As a result, countries in Europe (and others) confront a difficult choice: they can either witness a population decline, which leads to increased fiscal pressures from a growing number of retirees in proportion to the workforce, or they can welcome an influx of migrants, which may alter the societal fabric of the nation. The latter option becomes particularly challenging for smaller, homogenous countries, ethnically or religiously.
Consequently, resistance to immigration persists vigorously in numerous corners of Europe (and globally), providing fodder for populist figures seeking scapegoats.
Spain has generally adopted a more welcoming stance towards migrants, particularly under the leadership of Prime Minister Pedro Sanchez.
Approximately 19% of its population was born outside the country, contrasting with the EU’s average of 14% and the US’s 15.8%.
As many migrants come from Catholic and Spanish-speaking nations in Latin America, integration has appeared relatively straightforward compared to other European contexts. Still, the issue remains politically contentious.
The recent ‘invasion’ of Ceuta also exposed political rifts within Europe’s political landscape, with several leaders, including Italian Prime Minister Giorgia Meloni and Danish Prime Minister Mette Frederiksen, critiquing Spain’s approach.
They even suggested that Spain might face expulsion from the Schengen free-movement area.
This situation underscores Europe’s third geostrategic vulnerability, despite its collective population and wealth: fragmentation. Significantly improved military coordination is required to counteract the Russian threat, along with deeper integration of its multiple relatively small national capital markets to rival the scale and liquidity of US markets.
ADVERTISEMENT
CONTINUE READING BELOW
In the meantime, the interplay of immigration, population decline, and political backlash persists.
Recent anti-immigration demonstrations in South Africa, which included regrettable incidents of violence, should be evaluated in a global context. With a median age of 28, South Africa does not grapple with the same demographic decline. Yet, its status as a destination for migrants from neighboring impoverished regions is unlikely to change.
A silent rally
The final lesson is that a prominent theme isn’t always necessary for the market to rise.
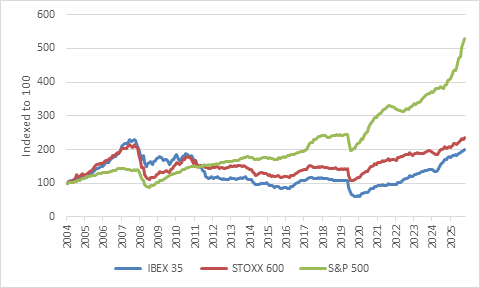
Over the last year, the Spanish equity market has significantly outperformed the tech-oriented US S&P 500, despite lacking high-profile companies or connections to the artificial intelligence narrative, the day’s hot topic.
The broader European Stoxx 600 index has also surpassed its US counterpart in dollar terms, achieving a quiet rally that has mostly escaped attention.
Equity benchmarks in US dollars
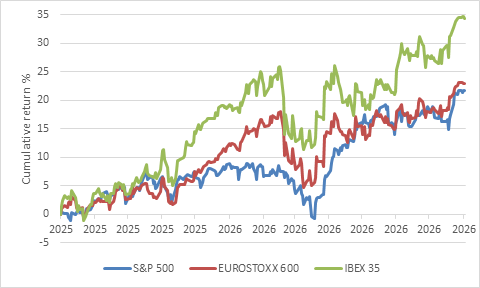
Source: LSEG Datastream
The explanation is straightforward: over time, stock prices align with earnings performance. Earnings growth in Spain and Europe was sluggish during the crisis years of the early 2010s, whereas US earnings growth remained more stable. However, over the past five years, Spanish equities have realized a 19% annual growth in earnings measured in euros from a low starting point.
Forward earnings per share in US dollars
Source: LSEG Datastream
Despite this growth, Spain’s IBEX Index trades at 14.2 times estimated earnings, in contrast to 20 times for the S&P 500. The Stoxx 600 trades at 14.8 times.
US equities justify a higher valuation given their consistent earnings records, but the valuation discrepancy between the two regions is now double what it has historically been.
For South African investors concerned about valuations in global equity markets, this serves as a reminder that some markets are trading at more reasonable levels.
The intention is not to encourage an immediate purchase of Spanish or European stocks but to emphasize that Europe’s shortcomings, including the absence of AI frontrunners and other systemic issues, do not render it an unviable investment landscape.
Moreover, this implies that markets like South Africa’s should not be dismissed due to economic struggles or a lack of direct exposure to AI. Instead, South African equities